What happened
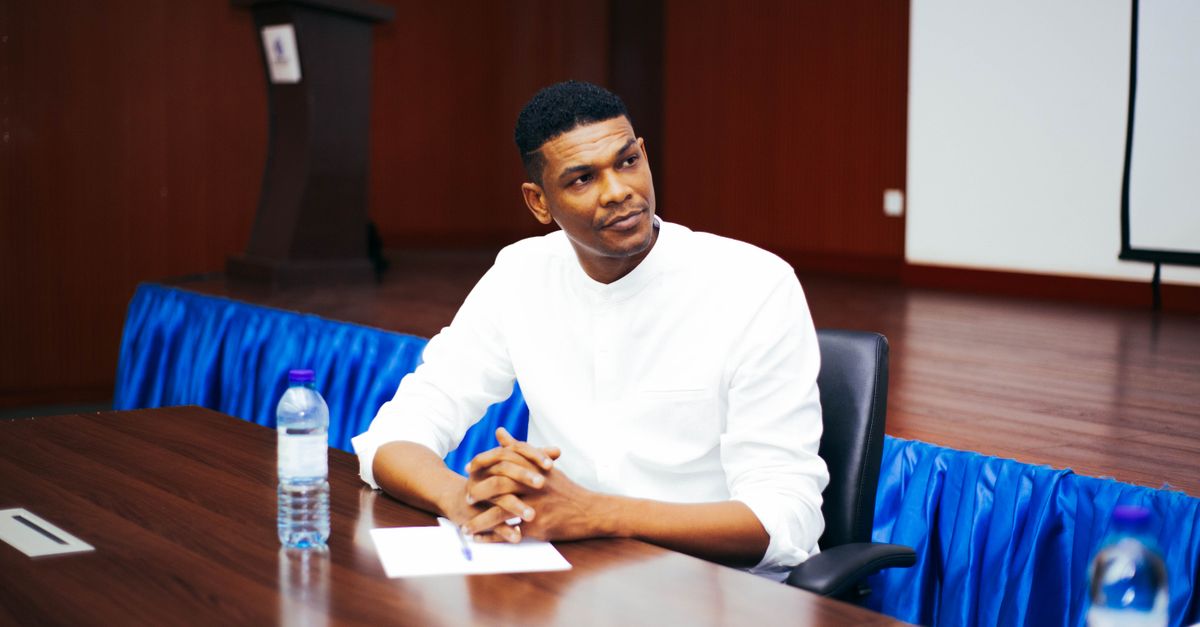
Abdi Mohamed has received formal approval from the Central Bank of Kenya (CBK) to assume the top executive role at I&M Bank Kenya. The appointment was reported by Soko Directory and marks the latest leadership change at one of Kenya’s mid‑size commercial banks. Mohamed steps into the role after the board’s recommendation and a regulatory vetting process that complies with the Banking Act. The bank has confirmed that Mohamed will take up his duties immediately, signalling a swift transition for its senior management team.
Context and background
I&M Bank Kenya, a subsidiary of the I&M Bank Group, operates a network of more than 30 branches across the country and serves a diverse client base that includes large corporates, micro‑enterprises and individual savers. The bank’s assets are estimated to be in the hundreds of billions of shillings, placing it among the top ten lenders in Kenya. Over the past few years, I&M has focused on digital banking, SME credit lines and expanding its presence in underserved regions.
The Central Bank of Kenya plays a statutory role in approving senior appointments at licensed banks to ensure that individuals meet fit‑and‑proper criteria. The approval process involves background checks, assessment of professional competence and verification of any potential conflicts of interest. In Mohamed’s case, the CBK’s clearance follows a board resolution that cited his extensive experience in banking operations, risk management and financial technology.
Abdi Mohamed’s career spans over two decades in the Kenyan financial sector. Prior to this appointment, he held senior positions at other commercial banks where he led credit portfolio management and digital transformation initiatives. His reputation for strengthening risk frameworks and improving loan recovery rates was highlighted by industry observers as a key factor behind the board’s decision.
Compared with what is normal
Leadership changes at Kenyan banks are not uncommon, but the speed of CBK’s approval for I&M Bank is notable. Typically, the regulatory clearance can take several weeks, especially when the candidate comes from a competitor. In this instance, the approval was announced within a short window after the board’s recommendation, suggesting a smooth vetting process.
- Average approval time for bank CEOs in Kenya: 4‑6 weeks.
- I&M Bank’s previous CEO transition took approximately eight weeks, involving a longer public consultation.
- Current market trend shows regulators fast‑tracking appointments to maintain stability in the banking sector.
- SME loan growth at I&M has averaged 12% annually; a change in leadership could accelerate or moderate this pace.
Why it matters
For Kenyan SMEs, the head of a bank often sets the tone for credit policy, risk appetite and the rollout of new financing products. Mohamed’s background in digital banking could mean a stronger push for online loan applications, faster disbursements and more data‑driven credit assessments. This may reduce processing times for small businesses that rely on quick access to working capital.
Existing borrowers should watch for potential revisions to interest‑rate structures or collateral requirements. A leader focused on risk mitigation might tighten underwriting standards, which could affect loan approvals for higher‑risk ventures. Conversely, his experience with recovery could lead to more flexible restructuring options for businesses facing cash‑flow challenges.
From an investor’s perspective, a clear succession plan and regulatory endorsement signal stability, which can bolster confidence among depositors and shareholders. The banking sector in Kenya is highly competitive; any shift in strategic direction at I&M could influence market share, especially in the SME segment where the bank has been actively expanding.
Practical steps
- Review your current loan agreements with I&M Bank to understand any clauses that may be affected by a change in credit policy.
- Engage with your relationship manager to inquire about upcoming product launches or changes in loan application procedures.
- Monitor I&M Bank’s public communications – newsletters, website updates and CBK bulletins – for announcements on interest rates or new financing schemes.
- Consider diversifying your financing sources if you rely heavily on a single bank, especially during leadership transitions.
- Strengthen your internal financial reporting to be ready for any tighter underwriting criteria that may be introduced.
Financial Management & Analysis services at Beavoren Ventures can help SMEs navigate the implications of this leadership change, from assessing loan terms to optimizing cash flow under new credit policies.
Book a consultation with Beavoren Ventures today and let us handle your compliance, books, and advisory in one place.
Disclaimer: This article is informational and does not constitute formal tax, audit or legal advice. For guidance specific to your circumstances, please contact Beavoren Ventures.