What happened
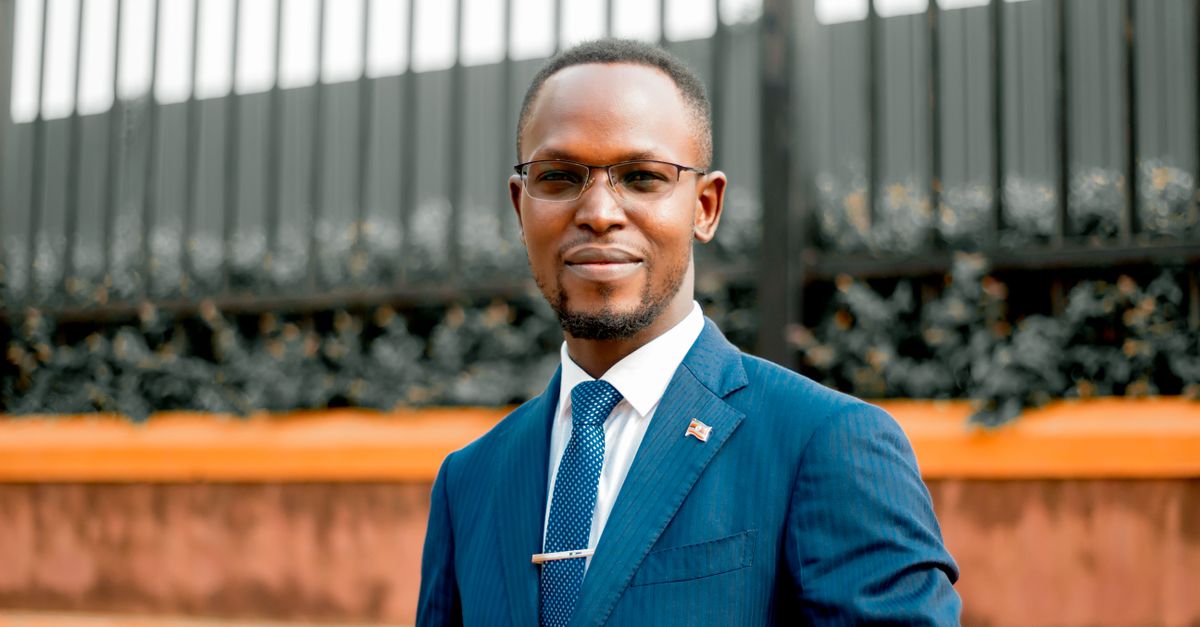
Abdi Mohamed has been confirmed as the chief executive officer of I&M Bank Kenya after receiving the required approval from the Central Bank of Kenya (CBK). The announcement was reported by Capital FM Africa and marks the latest leadership change at one of Kenya’s prominent commercial banks. The CBK’s nod is a statutory requirement for any new bank chief executive in the country, ensuring that the candidate meets regulatory fitness and propriety standards. Mohamed steps into the role at a time when the Kenyan banking sector is navigating post‑pandemic recovery and heightened competition for SME financing. The bank’s board issued a brief statement welcoming Mohamed and expressing confidence in his ability to drive growth. No detailed remuneration package or exact start date was disclosed in the initial release.
Context and background
I&M Bank Kenya, part of the I&M Group, has built a reputation for serving small and medium enterprises (SMEs) as well as retail customers across its network of branches in Nairobi, Mombasa, Kisumu and other key towns. The bank’s strategic focus on digital channels and tailored credit products has positioned it as a key player for wajasiriamali looking for flexible financing solutions. Over the past few years the bank has expanded its loan portfolio, introduced mobile banking enhancements, and pursued partnerships that deepen its reach into underserved markets. These initiatives have been driven by a leadership team that emphasizes risk‑aware growth while maintaining a strong capital base.
The appointment of a new CEO follows the resignation of the previous chief executive earlier this year, a move that prompted the board to initiate a thorough search for a successor with both local market insight and international banking exposure. In Kenya, the Central Bank must vet and approve any senior banking appointment to safeguard the stability of the financial system. The approval process typically involves a review of the candidate’s professional background, integrity, and fit with the bank’s risk appetite, after which the CBK issues a formal nod.
Abdi Mohamed brings to I&M Bank a wealth of experience gathered from senior roles at other Kenyan financial institutions, where he has overseen credit risk, operations and strategic planning. While the exact institutions he served at have not been listed publicly, industry observers note that his track record includes steering product innovation and strengthening governance frameworks. His background aligns with the bank’s ambition to deepen SME lending while enhancing digital service delivery, areas that have become increasingly critical as businesses adapt to new market realities.
Market analysts have noted that leadership continuity is crucial for banks that rely heavily on relationship‑based lending to SMEs. The transition is being watched closely by investors and corporate clients alike, who are keen to see how Mohamed will balance growth objectives with prudent risk management. Early reactions suggest optimism, with some commentators highlighting his reputation for collaborative leadership and data‑driven decision‑making. The bank’s shareholders are also expected to monitor how the new CEO’s strategies translate into profitability and asset quality over the coming quarters.
In the broader Kenyan banking landscape, recent years have seen several high‑profile CEO changes, reflecting both regulatory tightening and the sector’s evolving competitive dynamics. The CBK’s role in approving these appointments underscores the regulator’s commitment to ensuring that senior management possesses the requisite competence to navigate economic fluctuations, currency pressures, and the rapid digitisation of financial services.
Compared with what is normal
Typically, the CBK’s approval process for a new bank chief executive takes a few weeks, allowing time for background checks, verification of qualifications, and assessment of fit with the bank’s risk framework. In most recent appointments, banks have announced the appointment within a month of the regulator’s nod, aligning communication timelines with shareholder meetings and market disclosures. The I&M Bank appointment follows this conventional rhythm, with the announcement appearing shortly after the CBK’s formal approval.
- Standard regulatory steps: submission of candidate profile, background verification, fit‑and‑proper assessment, and issuance of approval letter.
- Typical timeline: 2‑4 weeks from submission to final approval, though complex cases can extend to six weeks.
- Common communication practice: public announcement within 5‑7 days of receiving the CBK nod to ensure market transparency.
Why it matters
The confirmation of Abdi Mohamed as CEO is significant for Kenyan SMEs and other borrowers because leadership direction influences credit policy, product innovation and the speed at which loan applications are processed. A CEO with a strong background in SME financing can accelerate the roll‑out of tailored loan products, potentially easing access to working‑capital finance for businesses that have been constrained by tighter credit conditions. Moreover, the bank’s commitment to digital transformation under new leadership could improve the efficiency of banking services, reducing transaction times for both corporate and individual customers. For investors and shareholders, stable and competent leadership reduces uncertainty, which can positively affect the bank’s share price and its ability to raise capital for future growth. Finally, the CBK’s endorsement reassures the market that the appointment meets the regulator’s standards for integrity and competence, a factor that underpins confidence in the stability of Kenya’s banking sector.
Practical steps
- Review your existing credit facilities with I&M Bank to understand any upcoming changes in terms or renewal processes under the new leadership.
- Engage with your relationship manager to discuss new SME‑focused products that may be introduced in the next quarter.
- Monitor the bank’s communications for announcements on digital banking enhancements that could streamline payments and cash‑flow management for your business.
- Consider conducting a brief internal risk assessment to ensure your financing arrangements remain aligned with your growth plans, especially if you anticipate applying for additional funding.
Financial Management & Analysis services at Beavoren Ventures can help your business interpret the implications of leadership changes at your banking partners, optimise cash‑flow planning and align financing strategies with evolving credit policies.
Talk to our team at Beavoren Ventures - info@beavorenventures.co.ke - to set up your systems correctly.
Disclaimer: This article is informational and does not constitute formal tax, audit or legal advice. For guidance specific to your circumstances, please contact Beavoren Ventures.